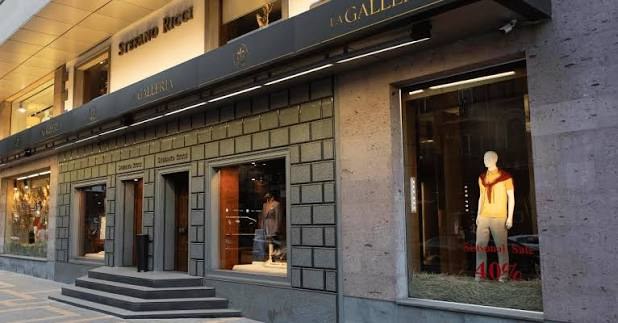
The State Revenue Committee (SRC) has uncovered a case of large-scale underreporting of sales turnover in the retail clothing sector.
During an analysis conducted by the department’s 15th division, data submitted in the company's tax returns were cross-referenced with various indicators reflecting its actual operational volume. Based on significant discrepancies, the company was assessed as high-risk, leading to the execution of targeted and large-scale investigative operations.
Within this framework, internal accounting documents were obtained from the company, as well as data of operational interest stored on office computers. The investigation revealed that the company, which retails luxury brand clothing in Yerevan, accepted cash payments for a portion of its sales without issuing corresponding cash register receipts and failed to include these transactions in its tax filings.
By cross-referencing the collected materials, it was determined that the company underreported its actual sales turnover in tax filings by approximately 9 billion 460 million AMD. The damage caused to the state budget has been calculated to exceed 1 billion 500 million AMD.

Following the SRC’s investigative measures, a report regarding the alleged crime was submitted to the Investigative Committee’s General Department for Investigation of Economic Crimes and Contraband. Based on this report, criminal proceedings were initiated, and urgent investigative actions were carried out.
A key feature of this case is that it does not merely involve a numerical discrepancy in tax filings; the SRC’s investigation also documented cash payments for which no receipts were provided. This circumstance explains how the substantial gap between declared and actual turnover was formed.
The process has now moved into the scope of criminal proceedings, and the outcomes of further investigative actions will be of critical importance in the next stage. Meanwhile, the figures presented in the article refer to the tax damage and underreported turnover calculated by the SRC; therefore, their final legal assessment must be linked to the future course of the proceedings.